


Bitcoin mining: Backbone of cryptocurrency, and its biggest problem
COMMENT | A few days after I submitted my previous article, the market capitalisation of cryptocurrencies plunged close to USD 423 billion on Dec 22, from an all-time high of slightly above USD 650 billion, just one day before – a whopping decline of 35 percent in 24 hours.
This came about as Emil Oldenburg, one of the founders of Bitcoin.org, publicly said that “an investment in Bitcoin right now I would say is the most risky investment you can make."

He explained that increasing transaction fees, as well as the fundamental problem of the underlying mining process, could defeat the noble reason behind bitcoin’s existence in the first place - to be a peer-to-peer electronic cash system for the masses.
Here, I will explain the mining process, the way cryptocurrencies work, and the problem mining imposes on the way cryptocurrencies will work in the long term. Although the mechanisms of the mining process differ across cryptocurrencies, they are fundamentally similar.
Mining is the process of validating cryptocurrency transactions. In the bitcoin network, miners compete to validate a block of transactions, and creating a new block in the network. To “win” this competition, miners are required to solve complex cryptographic problems.
Simply put, imagine you are given two numbers – for instance, 2 and 50 – and you are required to tell the system the answer of the product of these numbers, which is unique. In this case, it would be 100.
Now, what if you are given the digit 100, and you are required to let the system know of the two unique numbers which lead to the digit earlier? In this case, we have 1;100, 2;50, 4;25, 5;20 and 10;10. This is simple enough, but as the problems get more complex, it takes a bit of a time to find the right answer.
We can make this problem more complicated by increasing the value of digit (e.g., in the billions), adding restrictions to the answer (e.g., determining that 1;100 and 100;1 are two different answers), and adding more mathematical problems to it (graphical solutions, prime number factors, indices, etc.).
Now, it will take longer for you to solve the mathematical problem. These are the fundamental building blocks of cryptography. Each problem contains the detail of the thousands of transactions, which is required to be validated and solved – which the answer, a SHA-256 hash, a string of 64 letters and numbers, will reflect...
COMMENT | A few days after I submitted my previous article, the market capitalisation of cryptocurrencies plunged close to US$423 billion on Dec 22, from an all-time high of slightly above US$650 billion, just one day before – a whopping decline of 35 percent in 24 hours.
This came about as Emil Oldenburg, one of the founders of Bitcoin.org, publicly said that “an investment in Bitcoin right now I would say is the most risky investment you can make."
He explained that increasing transaction fees, as well as the fundamental problem of the underlying mining process, could defeat the noble reason behind bitcoin’s existence in the first place - to be a peer-to-peer electronic cash system for the masses.
Here, I will explain the mining process, the way cryptocurrencies work, and the problem mining imposes on the way cryptocurrencies will work in the long term. Although the mechanisms of the mining process differ across cryptocurrencies, they are fundamentally similar.
Mining is the process of validating cryptocurrency transactions. In the bitcoin network, miners compete to validate a block of transactions, and creating a new block in the network. To “win” this competition, miners are required to solve complex cryptographic problems.
Simply put, imagine you are given two numbers – for instance, 2 and 50 – and you are required to tell the system the answer to the product of these numbers, which is unique. In this case, it would be 100.
Now, what if you are given the digit 100, and you are required to let the system know of the two unique numbers which lead to the digit earlier? In this case, we have 1;100, 2;50, 4;25, 5;20 and 10;10. This is simple enough, but as the problems get more complex, it takes a bit of a time to find the right answer.
We can make this problem more complicated by increasing the value of digit (eg, in the billions), adding restrictions to the answer (eg, determining that 1;100 and 100;1 are two different answers), and adding more mathematical problems to it (graphical solutions, prime number factors, indices, etc.).
Now, it will take longer for you to solve the mathematical problem. These are the fundamental building blocks of cryptography. Each problem contains the detail of the thousands of transactions, which is required to be validated and solved – which the answer, an SHA-256 hash, a string of 64 letters and numbers, will reflect.
Not only does this provide the bitcoin system with security, it also provides “hype” for miners to compete with each other and solve the problem. Why? The first miner to solve it and come up with a new block will be rewarded with bitcoins.
The bitcoin reward for each block started off with 50 bitcoins in 2009, which halves for every 21,000 blocks formed. The block reward halved in 2012 to 25 bitcoins, and to 12.5 bitcoins in 2016. The next halving will occur in 2020. Putting in the formula of sum to infinity (geometric progression) and you will get the maximum number of bitcoin to ever be in existence; 21 million!
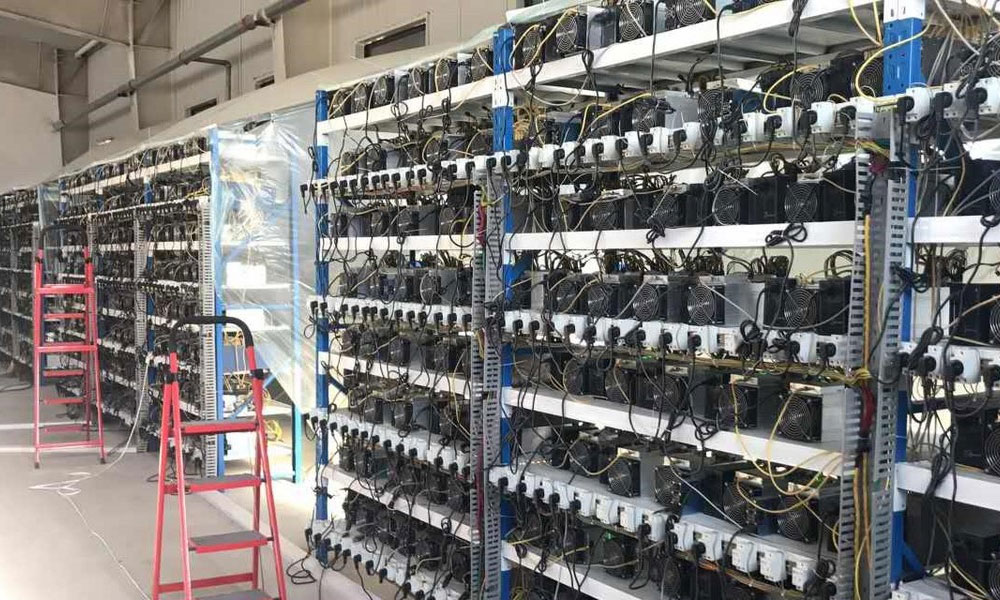
Let us now move on to the issues that the mining process imposes on the bitcoin network. Miners don’t solve the cryptographic problem manually. Instead, they use powerful computers to do the work.
While the fundamental idea is for the computer to solve the problem and submit the correct solution to the system, in reality, the computer simply submits a huge number of solutions per second, and is rewarded if the computer coincidentally submits the right answer.
Hence, miners invest in powerful central processing units and graphical processing units to run as many solutions per second as they can, so that the chances of them coincidentally submitting the right answers to the system increase.
This situation imposes two main problems. Firstly, these machines require huge capital investment, putting the capability of buying them solely in the hands of the rich. This defeats the fundamental decentralisation purpose of blockchain and cryptocurrency.
But as a common individual, I still can install small mining hardware in my house and join other miners around the world through mining pools. The mining pool gathers the power of our hardware and acts as a single miner to the system. Any reward that the mining pool gets will be distributed to its participant, in exchange for a fee.
Another fundamental point of blockchain and cryptocurrency is being defeated here. We have just created a new intermediary!
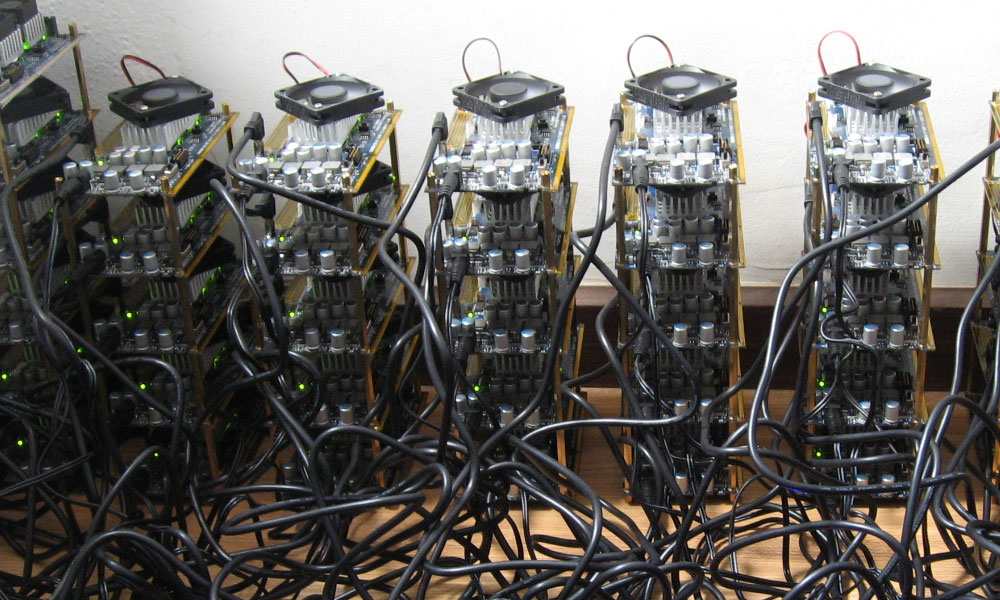
The second problem is the amount of electricity this kind of hardware needs. The statistics provided by Digiconomist are mind-blowing.
Putting aside humanitarian concerns – like how this amount of energy could be diverted to countries like India, parts of which do not even have 24-hour electricity supplies – this electricity comes as a monetary cost for the miners.
As soon as miners are rewarded with bitcoin, they have to partially sell their holdings to pay their electricity bill in fiat currency. This puts a downward pressure on the bitcoin price, which is detrimental to the bitcoin network in the long term.
In addition to the block reward, successful miners get transaction fee, which is autonomously determined and paid by the bitcoin sender. The halving of block reward and increasing number of transactions in the system puts upward pressure on the transaction fee (and miners need to make a profit after paying huge electricity bills).
Miners can, in fact, programme their hardware to selectively choose transactions which offer high transaction fee, neglecting those which offers low ones. The huge problem here is that when I submit my bitcoin transaction, I can never reverse it and hence, if the miners perceive my proposed fee to be low, I can no longer adjust it. My bitcoin will be stuck forever as an unconfirmed transaction.
Key figures around the world and numerous articles have been popping up of late, explaining how bitcoin is being “friendly” to those who can afford the transaction fee – which, as noted above, flies in the face of the reason bitcoin exists in the first place, a currency for the masses, not the super-rich.
In any case, it is astonishing how a public statement by one individual could rout the whole cryptocurrency market. I too no longer see the decentralisation benefit of cryptocurrency – especially when it comes to bitcoin.
NEXT
Hardfork, and alternative cryptocurrencies
PREVIOUS
The ABCs of cryptocurrency and blockchain
KAMRAJ SHANMUGANATHAN currently studies at the University of Warwick. He believes that knowledge asymmetry is the root of inequality in this world. He can be followed on @crypto.now, his cryptocurrency educational Instagram account.
The views expressed here are those of the author/contributor and do not necessarily represent the views of Malaysiakini.


Report this comment
Are you sure you want to delete this comment?
This action cannot be undone.