

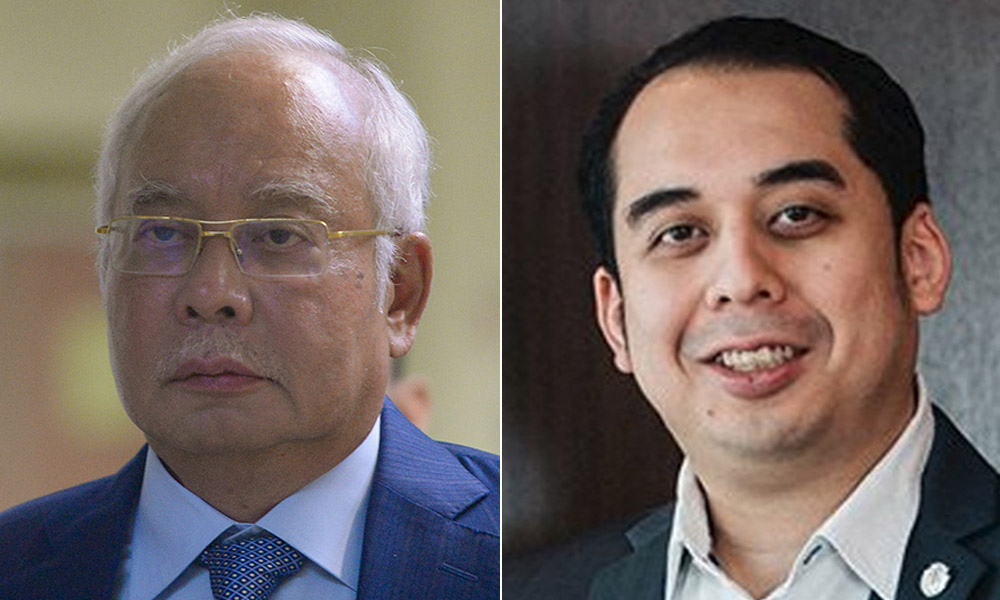

Najib, son go to Federal Court to quash tax suit ruling
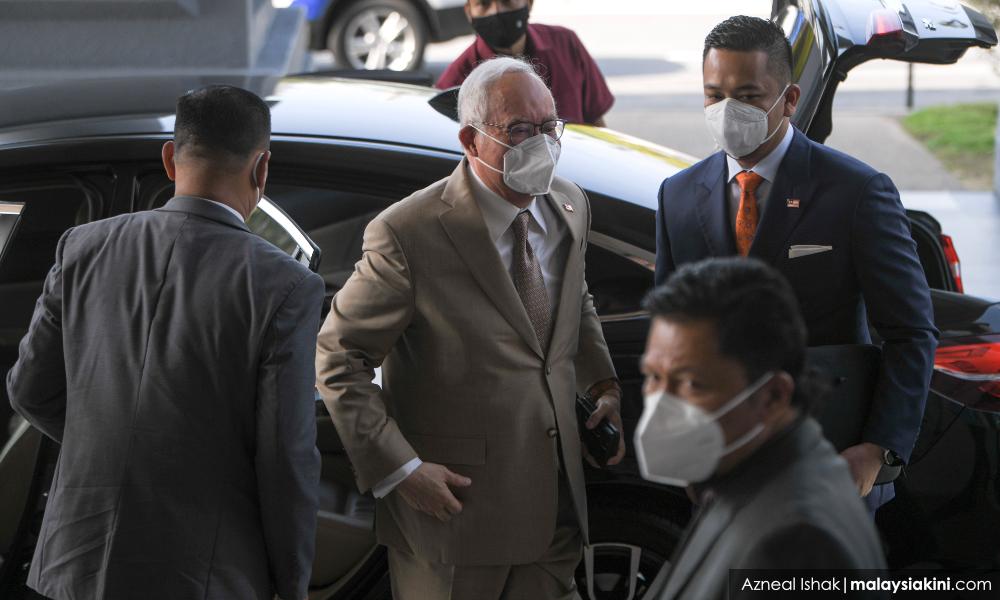
Najib Abdul Razak and his son Mohd Nazifuddin have gone to the Federal Court to overturn a High Court ruling in tax suits against them.
The legal team representing the former prime minister and Nazifuddin filed the appeal leave application to the apex court via an online e-filing system last night...
Najib Abdul Razak and his son Mohd Nazifuddin have gone to the Federal Court to overturn a High Court ruling in tax suits against them.
The legal team representing the former prime minister and Nazifuddin filed the appeal leave application to the apex court via an online e-filing system last night.
They are appealing against the Court of Appeal ruling on Thursday last week, which upheld the summary judgment rulings in the RM1.69 billion and RM37.6 million tax suits against Najib and Nazifuddin respectively.
Last year, two separate Kuala Lumpur High Courts allowed the Inland Revenue Board’s (IRB) application for summary judgment in the tax suits. In effect, this allowed the lower courts to rule in favour of the IRB in the tax suits against Najib and Nazifuddin, without needing full trial.
Relying on the summary judgment rulings, the IRB has since commenced bankruptcy proceedings against Najib and Nazifuddin to recover the tax arrears.
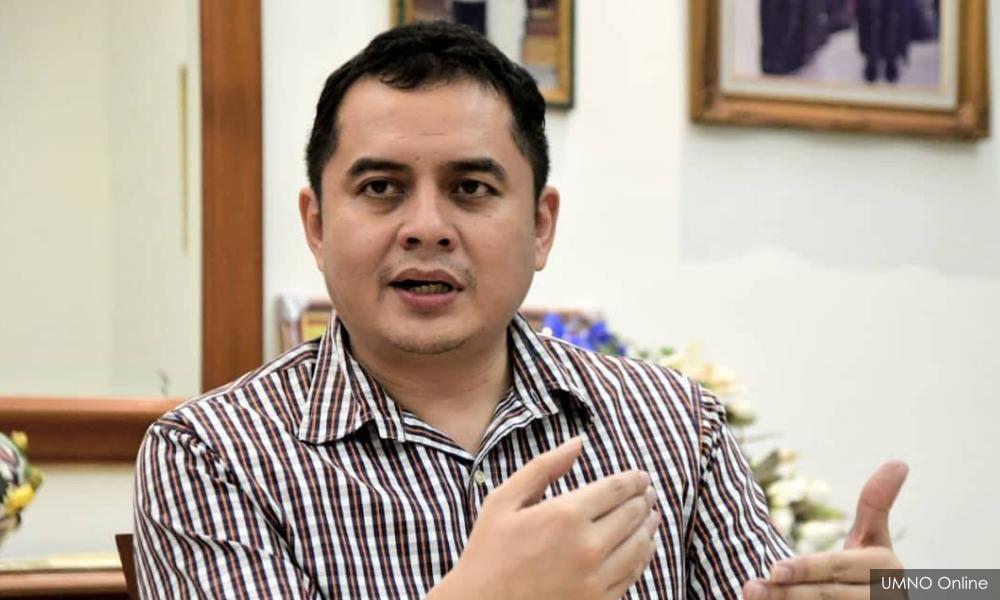
Speaking to Malaysiakini this morning, their lawyer Muhammad Farhan Muhammad Shafee confirmed that they filed the leave application online last night.
In Malaysia, the Federal Court needs to first determine whether leave should be granted to an appellant to commence with an appeal to the apex court. If leave is granted, another date will be fixed to hear the merits of the appeal.
“We filed the leave (to appeal application) to the FC (Federal Court) last night,” said Farhan.
The lawyer added that the legal team is in the midst of finalising an application for the Court of Appeal to stay the summary judgment, pending disposal of the appeal at the Federal Court.
“It (application for Court of Appeal to stay the summary judgment) will be in (filed) before the end of the day (today).
“We are appealing the Court of Appeal decision (to the Federal Court) as there are novel legal issues of public importance that impact the (Federal) Constitution.
“The arguments have never been decided by the Federal Court before, so we think it is a matter ripe for leave,” Farhan explained, adding that they have filed nine proposed questions of law for the apex court to decide on.
According to a copy of the leave application sighted by Malaysiakini, one of the nine questions of law is whether Section 106(3) of the Income Tax Act 1967 contravenes Article 121 of the Federal Constitution.
Section 106, in general, empowers the IRB to institute civil action at court to recover tax arrears and penalties from taxpayers.
Section 106 (3) specifically states that when in relation to IRB’s civil action to recover taxes, the court “shall not entertain any plea that the amount of tax sought to be recovered is excessive, incorrectly assessed, under appeal or incorrectly increased”.
Article 121 is in relation to the powers of the judiciary in Malaysia.
Najib and Nazifuddin’s legal team had contended that Section 106(3) is invalid as it usurped the power of the judiciary as enshrined in Article 121.
Najib also has a pending tax-reassessment appeal with the IRB’s Special Commissioners of Income Tax (SCIT), which is set to be heard in January next year.
Under Malaysia’s “pay first, talk later” tax practice, a dissatisfied taxpayer is still required to first pay the tax amount as assessed by the IRB, and then only file an appeal with SCIT for a reassessment of the tax amount.






Report this comment
Are you sure you want to delete this comment?
This action cannot be undone.